Getting into a car accident is a sudden and eventful situation to be placed, but on top of trying to recover from your injuries and determining how much you need to get everything fixed, you have to talk to an insurance adjuster whose sole role is to minimize your claim as much as possible.
Knowing how to deal with an insurance adjuster after a car accident depends on who the adjuster represents and the type of claim you are pursuing. While an adjuster working for your insurance provider may have different requirements than one handling a claim for the other driver’s insurer, understanding that difference can help you communicate carefully and give them the information needed without making statements that could hurt your personal injury claim.
Who Does the Insurance Adjuster Represent?
An insurance claim adjuster’s job is to represent the insurance company handling the claim and their role is to investigate the situation, assess the available evidence, look into the case, and determine how it will be addressed.
- First-Party Claims: If you are speaking with your own insurer, the adjuster represents your insurance provider.
- Third-Party Claims: If you are dealing with the at fault driver’s insurer, the adjuster represents that driver’s insurance company.
- Rideshare and Commercial Claims: Commercial or rideshare insurers (like Uber or Lyft) employ adjusters who specifically focus on protecting the company’s or policyholder’s commercial liability.
Keep in mind that an adjuster does not provide legal representation and cannot provide guidance on your behalf. Under California Insurance Code § 790.03(h), insurers are prohibited from engaging in unfair claims settlement practices, but their duty lies with their company, not your personal financial recovery. With that in mind, if you need someone to protect your interests or negotiate a disputed claim, an experienced attorney can assist you.
What Information Should You Have Ready Before the First Call?
Before speaking with an insurance company’s adjuster, have your contact details, claim number, and insurance policy information available. It also helps to have the basic details of the accident organized, like when and where it happened, who was involved, and what occurred.
Gather any accident scene photos and other necessary documentation like medical bills, repair estimates, and detailed records of expenses or treatment may support your claim beforehand, because it can help you answer questions with supported evidence without having to search for documents during the call.
You should also keep in mind the adjuster’s goal when discussing the claim, because they are gathering information to evaluate the insurer’s potential responsibility and the value of the claim. Stick to what you know, give them accurate answers, and avoid guessing when you do not have enough information to answer a question.
What Should You Avoid Guessing About?
While it is understandable to provide guesses on things you are unsure about, but it is recommended to avoid guessing what the full extent of your injuries are or if you suffered a new injury. Some symptoms may not show up right away, and you may need an evaluation to understand what actually happened.
Under California Civil Code § 56.10 (Confidentiality of Medical Information Act), your healthcare records are private, so let your providers assess your injuries and document how your progress is going when seeking medical treatment. Furthermore, it is vital that you do not admit fault or try to explain all the facts if you are not sure about the situation. Give the information you know without filling in the gaps with your assumptions.
Do You Have to Give a Recorded Statement?
If your own insurer reaches out to you, your policy may require you to cooperate with the investigation, which could include answering questions or sharing a recorded statement. However, if the at fault driver’s insurer or another insurer contacts you, your obligations may be different, and you should not assume that you are required to participate.
What To Do When Talking with an Insurance Adjuster
When an insurance adjuster calls and asks to record your statement, you can ask what the statement is for and whether it is needed. If you are unsure, you can politely decline to provide one at that given time and seek legal advice before moving forward. You can also say to an insurance representative that you would prefer to review the request first.
Keeping track of phone calls and other adjuster contacts can help you communicate effectively and keep a record of what was talked about. Because the requirements can vary based on the insurer and policy terms, there is no single answer that applies to each and every claim.
Should You Sign a Medical Authorization From the Insurance Company?
If an insurance company is asking you to sign a medical authorization form, you should review it thoroughly before you sign it because an authorization may allow the insurer to get your medical records as part of the claims process.
However, the scope of what it allows can vary because a broad authorization may raise privacy concerns under California Civil Code § 56.10 if it gives the insurance company access to medical information that has little or no connection to the car accident. Instead, an injured party may utilize California Evidence Code § 1158 to provide relevant medical records through an attorney or representative.
How Does Medical Records Factor in?
Medical records can help influence the insurance company’s decision about liability, the extent of an injury, and the value of a claim. Providing the right details can also demonstrate that the claim is being handled in good faith.
However, you do not have to sign a blanket authorization that gives an insurance company unlimited access to your entire medical history just because they are requesting a release. If you are uncertain about the scope of an authorization or what records the insurer is seeking, consider reviewing it with a California car accident attorney before signing.
What Is a Settlement Release and Why Does It Matter?
A settlement release is a legal document you may be asked to sign when accepting a settlement offer. It typically confirms that you agree to resolve the claim in exchange for payment and release the insurer or other responsible party from further legal action arising from the car accident.
Because signing a release can make a settlement final, it is important to understand what rights you are giving up before moving forward. Under California Civil Code § 1542, a general release typically does not cover claims that you do not know or suspect exist when you sign it. However, a settlement agreement may include language that waives these statutory protections. This is why it is important to carefully review the language of a release before signing it.
What to Consider Before Signing a Settlement Release
Before accepting what you believe is a full and fair settlement, consider whether your injuries, treatment needs, lost income, property damage, and other losses have been fully understood. This includes economic damages, like medical bills or loss of earning capacity, and non-economic damages, such as pain and suffering, where applicable. If your medical recovery is still uncertain, avoid settling until you have better knowledge of the potential impact.
The insurer pays the agreed settlement in exchange for resolving the claim according to the release. Reviewing the document carefully before signing can help you understand exactly what is being addressed and whether the proposed settlement covers the losses you are seeking to recover.
What If the Adjuster Says You Were Partly at Fault?
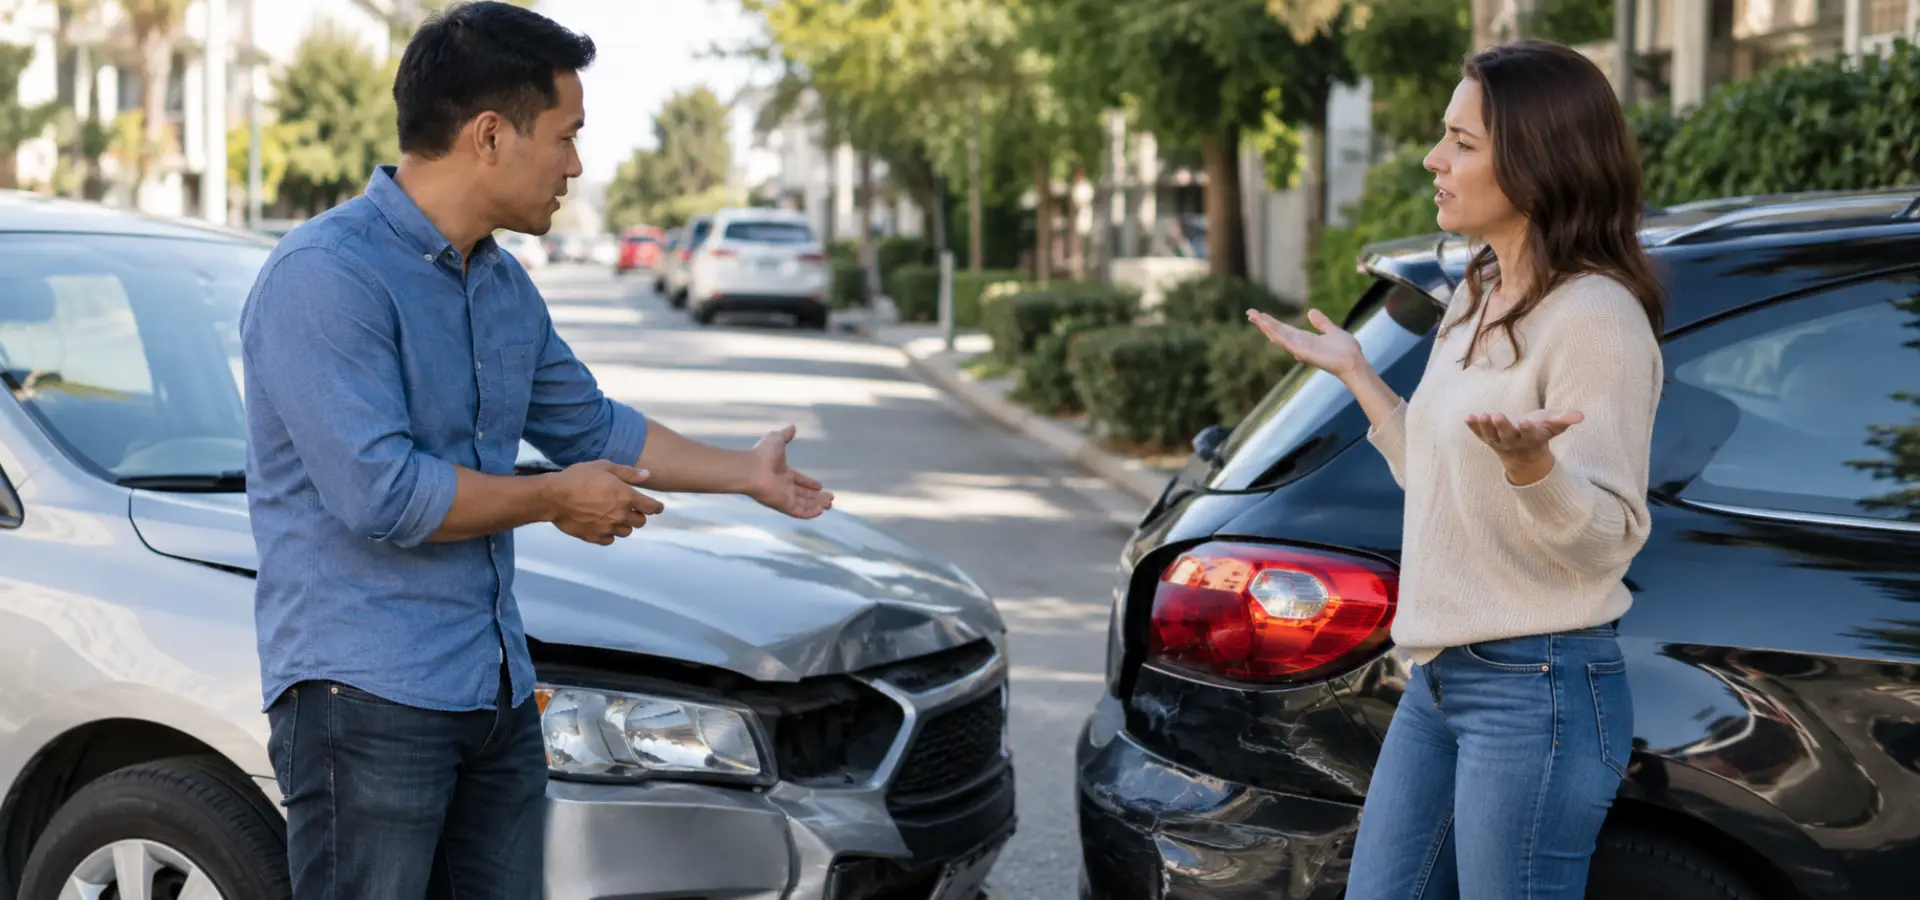
If an insurance adjuster’s assessment indicates you were partly at fault, it is not necessarily the final determination of responsibility. The insurer may be evaluating the available evidence when deciding how to handle your injury claims. Under California’s pure comparative negligence system, a person’s recovery can be reduced based on their percentage of fault for the car accident (as established in Li v. Yellow Cab Co. (1975)).
Rather than accepting or disputing the adjuster’s assessment, consider the evidence supporting each party’s position. Photographs, witness statements, a police report, vehicle damage, and other records may help determine what happened and whether the proposed allocation of fault is supported by the facts presented.
How Should You Respond to a Low Offer?
If an insurance company’s decision results in an initial offer that seems too low, review the adjuster’s assessment and the information used to calculate the amount. An insurer may offer as little money as it believes is supported by its evaluation of the claim, which may not cover all of your documented losses or may be based on incomplete or inaccurate information.
If you believe the offer does not reflect a fair settlement, supporting your position with documentation can help the insurer reconsider the amount of fair compensation available for your claim. However, keep in mind the deadline under California Code of Civil Procedure § 335.1, which gives you two years from the date of the accident to take legal action if negotiations stall. If the dispute involves significant damages or questions about liability, consider seeking legal guidance from an experienced car accident lawyer before accepting or turning down the offer.
When Should You Consider Legal Help With the Insurance Company?
You may want to consider legal counsel if you suffered a serious injury, the parties dispute fault, the claim involves complicated coverage issues, or a commercial defendant is involved. Professional guidance may also be helpful when you are dealing with heavy losses, such as medical bills or lost wages, or when an insurance company is challenging the worth of your claim.
With more than 25 years of collective legal practice and over $2 billion recovered for our clients, West Coast Trial Lawyers has an experienced team ready to review your claim, communicate with the insurer, gather supporting evidence, and help you understand your options. Having representation can also make the claims process more manageable while giving you time to focus on your recovery along with other responsibilities.
If an insurer is disputing your claim, offering you less than what you believe you deserve, or is making the process difficult to manage, you do not have to handle it all on your own. For legal support, we invite you to connect with us today to book a FREE consultation by calling (213) 927-3700 or filling out our convenient online contact form.
This article is for informational purposes only and does not constitute legal advice. Always consult an attorney about your individual case.