Getting hurt because someone else was careless is stressful enough, but figuring out how to actually hold them accountable, while you are dealing with medical bills, missed work, and recovery, can feel impossible. The good news is that the process follows a predictable path, and knowing the steps ahead of time puts you in a far stronger position.
This is a plain-English, step-by-step guide to filing a personal injury claim in Arizona. It covers what to do first, the deadlines that can make or break your case, how Arizona divides fault, and what happens if the insurance company will not play fair.
What Is a Personal Injury Claim?
A personal injury claim is how an injured person seeks compensation from whoever caused their harm, usually through that person’s insurance company. It can arise from a car crash, a slip and fall, a dog bite, a defective product, medical negligence, and more.
The goal is to recover your financial losses, medical costs, lost wages, and the physical and emotional toll, from the party at fault. Most claims settle without ever reaching a courtroom, but the ones that succeed are built carefully from day one.
Step 1: Get Medical Care and Keep Every Record
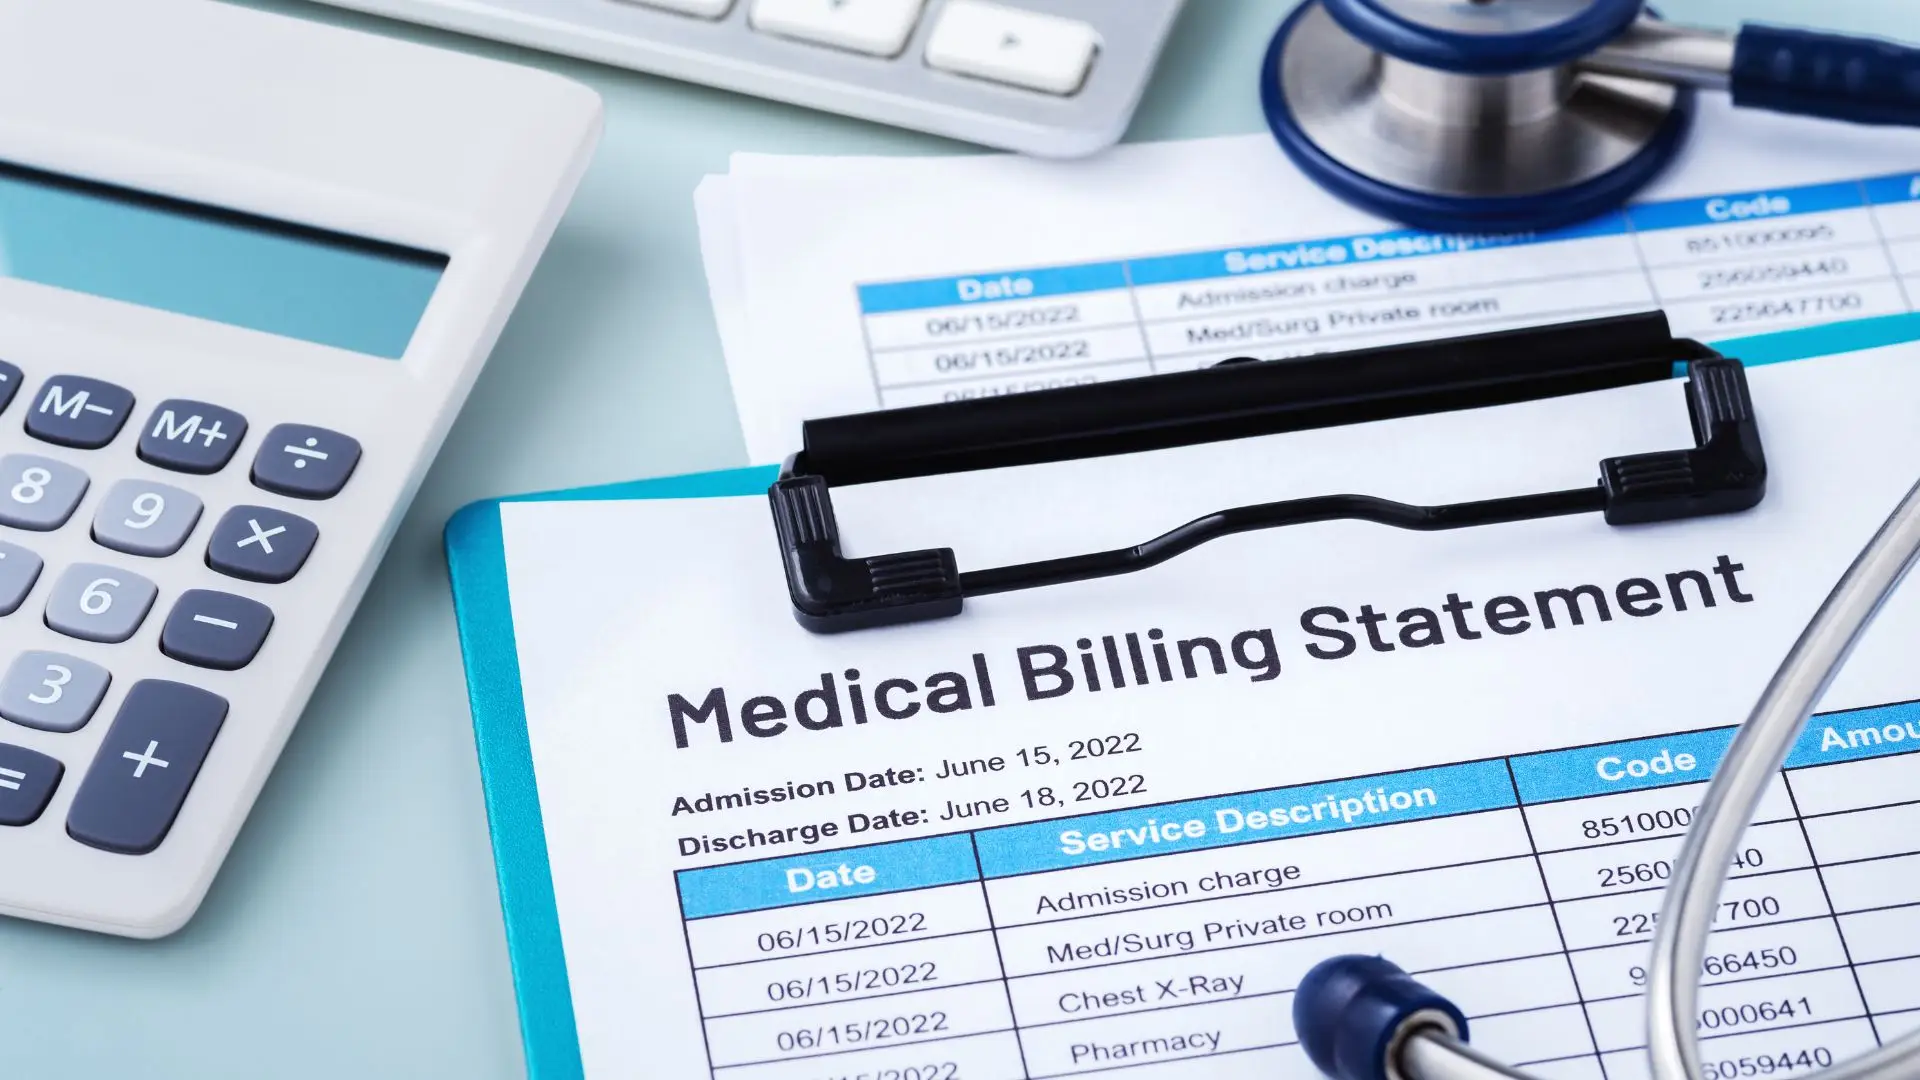
Your health comes first, and so does the paper trail. See a doctor as soon as possible, even if you feel “mostly fine,” because injuries like concussions, soft-tissue damage, and internal trauma often surface hours or days later. Beyond protecting your health, prompt treatment creates the medical record that ties your injuries directly to the incident.
Keep everything:
- Bills, discharge papers, and treatment plans
- Prescriptions and therapy records
- A simple journal of your pain, symptoms, and how the injury affects daily life
Gaps in treatment are one of the first things an insurance adjuster will use to argue you were not really hurt and the best ways to combat this is consistent care that tells the true story.
Step 2: Document the Scene and Preserve Evidence
The strength of your claim often comes down to evidence, and much of it disappears fast. As soon as you are able, or with the help of someone you trust, gather:
- Photos and video of the scene, your injuries, and any property damage
- The names and contact information of every witness
- A copy of the police or incident report
- Any surveillance or doorbell footage nearby, which can be overwritten within days
If your injury happened on someone’s property or involved a vehicle, note the conditions: lighting, hazards, weather, and anything that contributed. The details you capture now are the details a fair settlement is built on later.
Step 3: Know Your Deadline, and the 180-Day Government Trap
This is the step that trips people up because Arizona sets strict deadlines called statutes of limitations, and once they pass, your claim is gone for good. For most personal injury claims in Arizona, you have two years from the date of injury to file a lawsuit, under ARS 12-542 and that covers car accidents, slip and falls, and most negligence cases.
But if your claim is against a government entity, a city, county, the state, a public school, or a government employee, the rules are far shorter and stricter:
- You must file a formal notice of claim within 180 days of the incident under ARS 12-821.01.
- You then have only one year to file the lawsuit under ARS 12-821.
Miss that 180-day notice, and you can be permanently barred from suing, even though the normal deadline would have given you two years. This catches injured Arizonans off guard constantly, especially in crashes involving a city bus or an injury on public property. A few other details that can change your timeline are injuries to minors generally toll the clock until age 18, and the “discovery rule” can delay the start date when an injury was not immediately apparent.
Step 4: Figure Out Who Was at Fault
Arizona follows pure comparative negligence under ARS 12-2505. This rule is important, and it works in an injured person’s favor. Under it, you can recover compensation even if you were partly to blame for the accident, but your financial recovery is simply reduced by your percentage of fault.
Here is a quick example. If your damages total $100,000 and a jury finds you were 20% at fault, you still recover $80,000. Even a person found mostly at fault can recover the remaining share, as long as they are not 100% responsible.
This is also exactly why insurance companies fight so hard to pin fault on you. Every percentage point they shift onto you comes straight out of your recovery, which makes the evidence you gathered in Steps 1 and 2 so valuable.
Step 5: Notify the Insurance Company, Carefully
You generally need to report the incident to the relevant insurance company promptly. But how you communicate matters enormously.
- Do notify them and provide the basic facts.
- Do not give a recorded statement before getting legal advice.
- Do not accept a fast, early settlement offer, which is almost always far below what your claim is worth.
- Do not downplay or guess about your injuries, since symptoms can still be developing.
Adjusters are trained, and paid, to settle for as little as possible. A friendly call asking you to “just walk me through what happened” is not casual conversation; it is evidence-gathering. Say only what is necessary and factual.
Step 6: Add Up Your Damages
Before you can pursue fair compensation, you have to know what your claim is actually worth. Arizona lets injured people recover two broad categories of damages:
- Economic damages: medical bills, future medical care, lost wages, lost earning capacity, and property damage
- Non-economic damages: pain and suffering, emotional distress, and loss of enjoyment of life
One notable advantage for injured people in Arizona: the state constitution prohibits laws that cap the amount of damages you can recover for an injury or death. Unlike some states, Arizona does not limit what a jury can award, which protects people with catastrophic, life-changing injuries. Valuing a claim accurately, especially future costs and non-economic harm, is one of the hardest and most important parts of the process.
Step 7: Send a Demand and Negotiate
Once your treatment has stabilized and your damages are clear, the claim usually moves to a written demand. This is a formal letter to the at-fault party’s insurer laying out the facts, the liability, your injuries, and the compensation you are seeking, backed by the evidence.
From there, negotiation begins. The first offer is rarely the last, and back-and-forth is normal. A well-documented demand supported by strong evidence is what gives you leverage. Most Arizona personal injury claims resolve at this stage, without a lawsuit ever being filed.
Step 8: File a Lawsuit If a Fair Offer Never Comes
If the insurer refuses to offer a fair amount, the next step is filing a lawsuit in Arizona civil court, before your deadline runs. Filing does not mean your case will end up in front of a jury. It opens a new phase:
- Discovery, where both sides exchange evidence, documents, and sworn testimony
- Mediation or settlement talks, which resolve the large majority of filed cases
- Trial, only if no fair resolution is reached
The simple reality is that a claim backed by a firm willing to go to trial tends to command more serious settlement offers. Insurers pay attention to who is actually prepared to see it through.
You Do Not Have to Navigate This Alone
Every step above can be done on your own, but each one is also a place where a small mistake, a missed deadline, an offhand comment to an adjuster, an undervalued claim, can quietly cost you thousands of dollars or your case entirely.
At West Coast Trial Lawyers, our experienced team of Arizona injury attorneys handles the entire process so you can focus on healing. The firm has recovered more than $1.7 billion for injured clients, and attorneys including former federal prosecutor Neama Rahmani know how to confirm your exact deadline, preserve the evidence, build a full-value claim, and push back when insurers stall or lowball.
Call (213) 927-3700 or fill out our online contact form for a free, no-pressure consultation. On top of it all, we operate on a contingency-fee basis, meaning you do not pay any legal fees unless we win!